 Tagesgeld-Konto.net Tagesgeld-Konto.net — Ein mächtiger Strom beginnt oft mit einer beständigen Quelle, doch erst die intelligente Kanalisierung der gewaltigen.
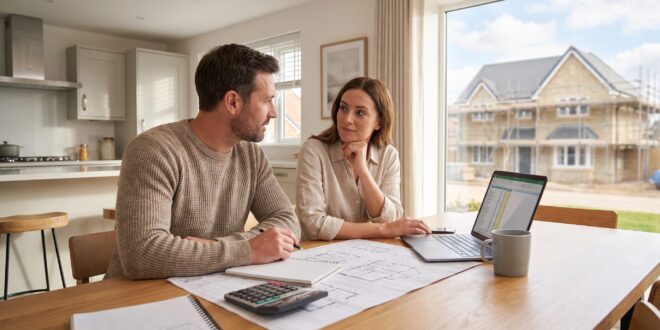
A powerful river profoundly shapes the geography of its surroundings over decades, just as a massive capital injection models the long-term asset structure of a private household. When we channel the enormous financial flows through intelligent dams and well-calculated channels, the entire economic valley flourishes in sustainable stability. However, if we let the flow run uncontrolled, unpredictable erosions of the financial base threaten to undermine the painstakingly built foundation. Especially in Europe, we are currently feeling the rough currents triggered by the dynamic interest rate policies of central banks. European borrowers face the highly complex task of navigating these volatile waters to safely and profitably bring their capital to its destination. This is precisely where a precise €300,000 loan calculator serves as our indispensable hydrological measuring instrument. It allows us to accurately calculate the flow rate of capital before we plunge into extensive construction financing.
The use of such an instrument is far more than a simple mathematical exercise; it is a fundamental act of financial self-defense and strategic asset planning. A €300,000 loan calculator transforms invisible interest risks into clear, manageable parameters for our long-term wealth accumulation. We not only visualize the monthly burden but also simulate the entire life cycle of the loan. Through systematic analysis of terms, repayment rates, and nominal interest rates, we take control of our liquidity. At Tagesgeld-Konto.net, we follow the clear philosophy that only those who understand the flow mechanics of their money achieve true financial sovereignty. Those who wisely adjust the parameters of real estate financing protect themselves from unexpected floods in the form of interest escalations while simultaneously securing room for lucrative reinvestments.
Architecture of Payment Flows: Technical Analyses
To accurately gauge the depth of the fairway, we must precisely deconstruct the mechanical variables of a large-volume loan. The following technical analyses illuminate the critical levers that determine the success or failure of real estate financing.
How does the initial repayment rate affect the total term for a volume of €300,000?
The initial repayment rate is the engine that drives the capital through the riverbed. In an annuity loan, the monthly rate remains constant, but the ratio between interest and repayment shifts continuously. When we operate a €300,000 loan calculator and set a standard repayment of just one percent with an assumed effective interest rate of four percent, the water flows extremely sluggishly. In this scenario, the total term would exceed a shocking forty years, and the accumulated interest burden would massively inflate the original loan amount. However, if we increase the initial repayment to a pragmatic two or even three percent, the debt reduction accelerates exponentially. A detailed repayment plan reveals that increasing the repayment by just one percentage point can shorten the term by more than a decade. This not only saves tens of thousands of euros in interest costs but also reduces the risk of being in retirement age.
Ich bin total begeistert von diesem Kreditrechner! Endlich mal ein Tool, das wirklich durchdacht ist und mir hilft, meine Finanzen besser zu planen.
Bonjour à tous! Ich bin total begeistert von diesem Kreditrechner. Ich hab ihn gerade für meine eigene Planung genutzt und die Klarheit, die er bringt, ist einfach unbezahlbar. Es ist so beruhigend zu sehen, wie sich verschiedene Szenarien auf die monatliche Rate auswirken. Absolut empfehlenswert für jeden, der gerade eine große Finanzierung plant!